Squarespace Template for Mortgage Brokers: Rules First, Design Second
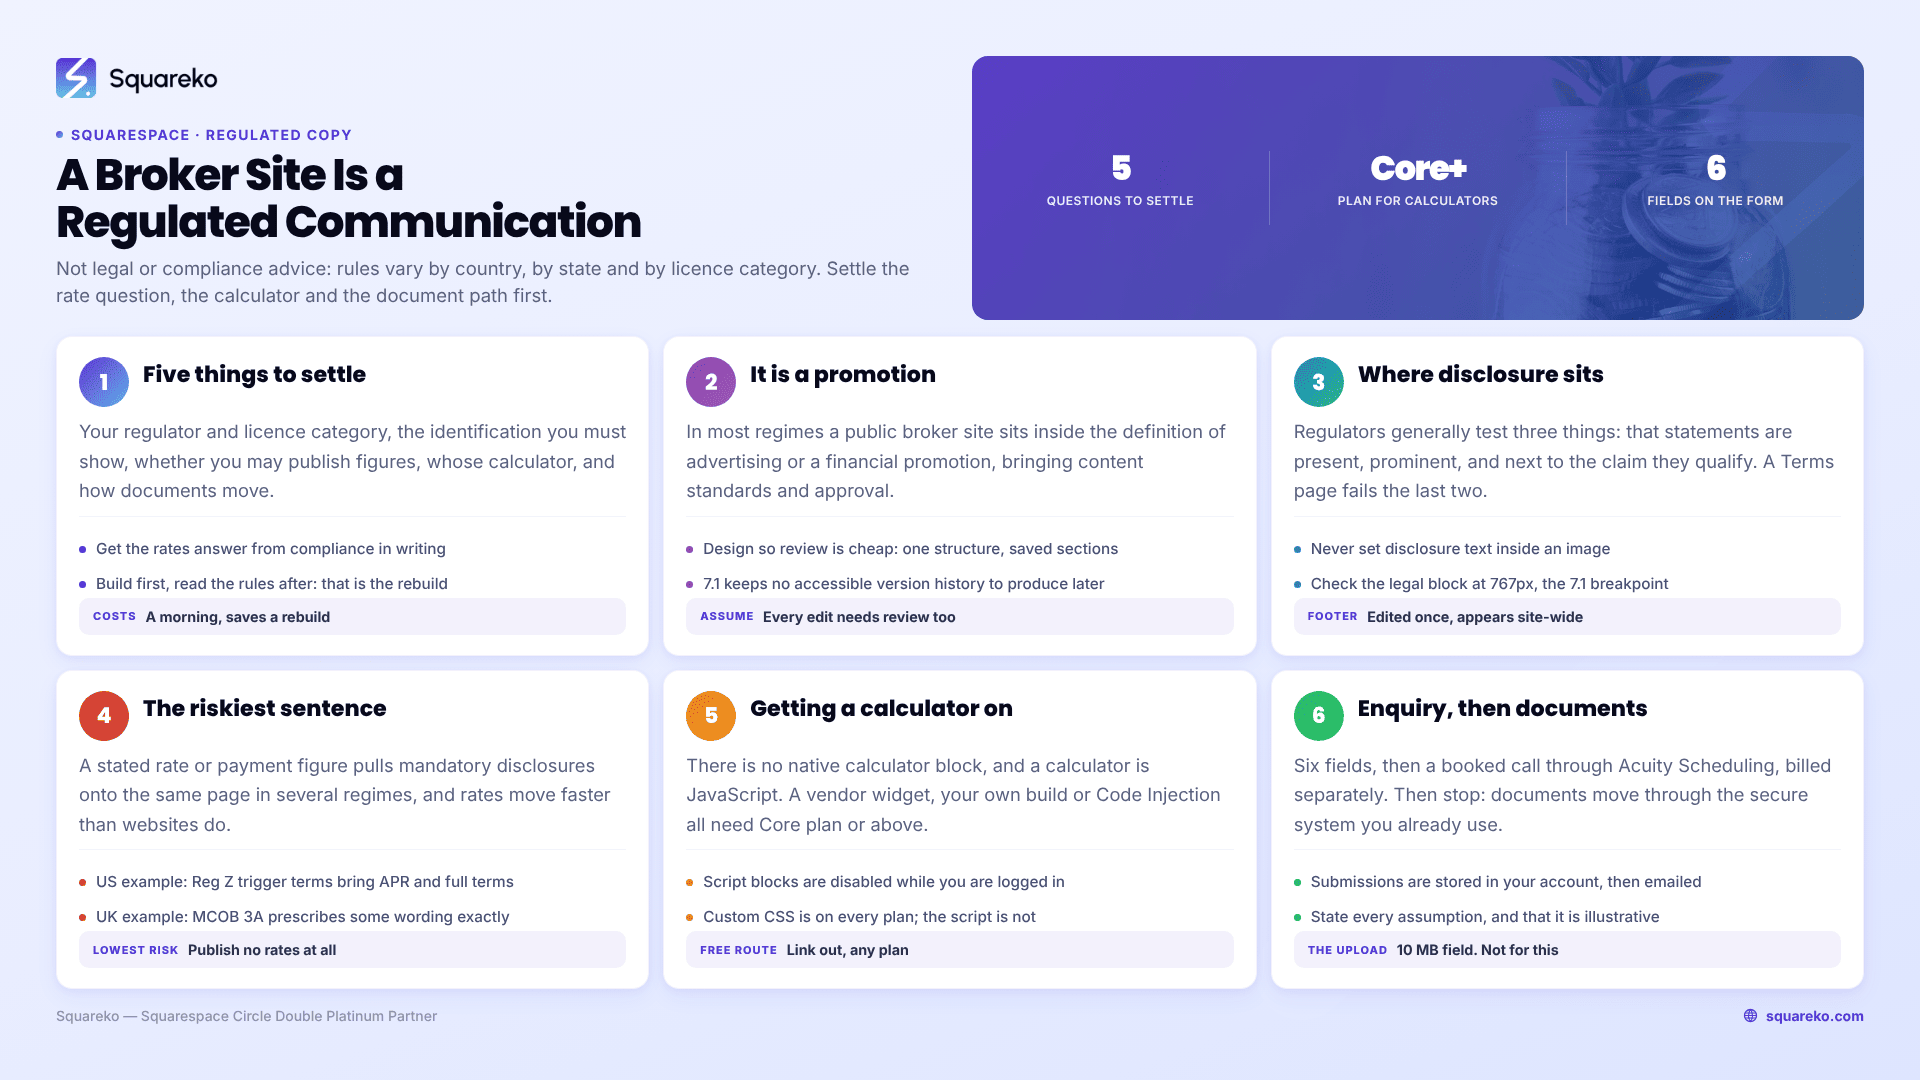
The short answer: a mortgage broker's website is a regulated communication before it is a marketing asset, and two decisions shape the whole build — what you are permitted to say about rates and repayments, and how the calculator gets onto the page. The calculator is a script, and JavaScript and iframes inside Squarespace Code Blocks require the Core plan or above. Settle both before you look at a template.
This post is not legal, regulatory or compliance advice. Mortgage advertising rules vary substantially by country, by state or province, and by whether you are a licensed mortgage loan originator, an appointed representative of a principal firm, a directly authorised broker, or an introducer who passes leads on. Everything below is general practice to check against your own regulator's rules and your own compliance function. Where a specific rule is named, it is named as an example of one regime, not as a universal.
Five things to settle before you choose a template
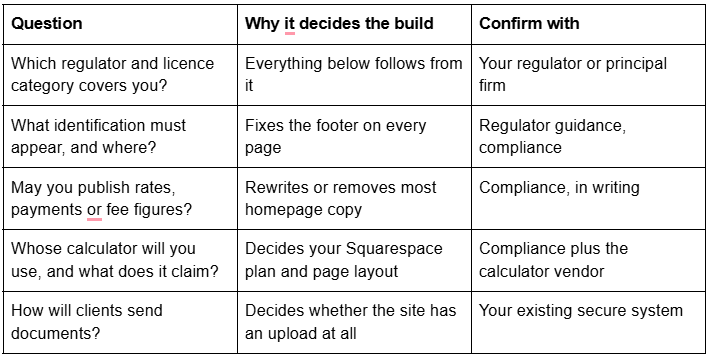
The pattern in broker website projects that go wrong is always the same: the site gets designed, written and built, then someone reads the promotion rules and half the copy comes out. The table above costs a morning and saves a rebuild.
Your website is a financial promotion, not a brochure
In most regimes, a public-facing mortgage broker website falls inside the definition of advertising or financial promotion, which brings content standards, and often approval and record-keeping expectations, with it.
Two examples of how differently regimes handle the same page:
United States. Advertising for closed-end credit sits under Regulation Z. Section 1026.24(d) sets out trigger terms: if an advertisement states the amount or percentage of a downpayment, the number of payments or period of repayment, the amount of any payment, or the amount of any finance charge, then the advertisement must also disclose the downpayment amount or percentage, the terms of repayment reflecting the obligation over the full term including any balloon payment, and the annual percentage rate, using that term — with a statement that the rate may increase if it can. Section 1026.24(c) adds that a simple annual or periodic rate may be stated alongside the APR but not more conspicuously than the APR. Separately, most state regimes require a licensed mortgage loan originator's identifying number to appear on advertising; confirm the exact form with your state regulator.
United Kingdom. A promotion of qualifying credit must meet the FCA's standard in MCOB 3A.2.4 — a firm must be able to show it took reasonable steps to ensure a non-real-time financial promotion is fair, clear and not misleading, with a stricter absolute duty for MCD-regulated mortgage contracts, which must not contain wording creating false expectations about availability or cost. MCOB 3A.2.6 also prescribes terminology: an early repayment charge must be described as an "early repayment charge" and nothing else, a higher lending charge as a "higher lending charge", a lifetime mortgage only as a lifetime mortgage, and a sale and rent back agreement must not be described as equity release.
The build consequence is identical in both cases: assume every public page needs review before it goes live, and assume edits need review too. So design the site so review is cheap — one consistent page structure, disclosures in reusable saved sections, and no clever one-off layouts that force a reviewer to re-read the whole site every time you change a heading.
One Squarespace-specific gap to close early: Squarespace 7.1 keeps no accessible version history of published page content that you could produce to a regulator. If your regime imposes retention obligations on promotions, that has to be handled deliberately — a third-party website archiving service, or dated PDF captures of every public page at each approved revision, starting on launch day. Retro-fitting an archive after two years of edits is not possible.
Identification and disclosure: placement matters as much as wording
Regulators generally test three things: that the required statements are present, that they are prominent rather than buried, and that they sit next to the claim they qualify. A disclaimer that only exists on a Terms page fails the second and third tests.
On Squarespace 7.1 the structure that works:
A site-wide footer carrying the registered legal entity name rather than the trading brand, company or registration number, licence or firm reference identifiers as your regulator requires, the general risk statement, and links to privacy, terms and complaints. Squarespace footers are edited once and appear everywhere, which is exactly the behaviour you want.
Page-level qualifying text directly beneath any specific claim, at body-copy weight. Build it as a saved section so wording cannot drift between pages.
Never inside an image. Disclosure text set into a graphic is invisible to screen readers, unselectable, unsearchable, and impossible to evidence later.
Check the footer at 767px, Squarespace 7.1's mobile breakpoint. A legal block is the element most likely to collapse into an unreadable line on mobile, and mobile is where most of your traffic reads it.
Shrinking disclosures to 9px is a recognisable pattern, and regulators recognise it. Keep them legible and design around them.
Rates: the single riskiest sentence on a broker's website
"Rates from 4.29%" is the sentence that causes most of the trouble, because in several regimes stating a rate or a payment figure pulls a set of mandatory disclosures onto the same page — and because rates move faster than websites do.
Three practical positions, in ascending order of risk:
Publish no rates at all. Talk about process, criteria, lender panel breadth and what you charge for your own service. Almost always the right answer for a small brokerage, and it removes an entire maintenance burden.
Publish an illustrative example with the full required disclosure set, dated, and with a documented process for updating or removing it. Only worth it if rates are genuinely your differentiator.
Publish a live rate table fed by a third-party feed. This is a script embed, with everything that implies for your plan, and you are now responsible for a claim generated by someone else's data.
Whichever you choose, the broker fee position should be stated plainly — whether you charge the client, whether you are paid by the lender, or both. That sentence builds more trust than any rate does, and it survives review.
Calculators: how they actually get onto a Squarespace page
Every mortgage broker wants a repayment calculator, and this is where the platform constraint bites.
Squarespace has no native calculator block. A calculator is JavaScript. There are four real routes:
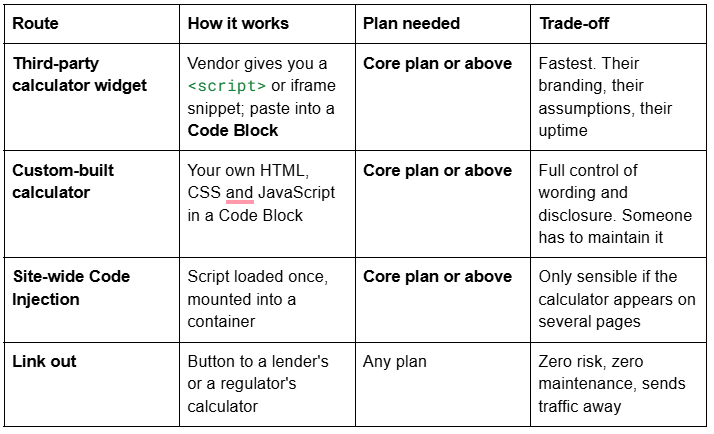
Two behaviours to expect rather than debug:
Script-bearing Code Blocks are disabled while you are logged in. Squarespace shows: "This block contains embedded scripts. Embedded scripts are disabled while you're logged in and editing your site." That is not an error and the calculator is not broken. Use Preview in Safe Mode, or log out, before you conclude anything.
Custom CSS is available on every plan; the JavaScript is not. You can style a calculator's container on any plan through Website → Website Tools → Custom CSS. It is the script itself, and iframes, that need Core or above. Brokers on the entry-level plan regularly discover this after buying a calculator subscription.
A note on mobile: calculators are used on phones far more than on desktops, and third-party widgets frequently render at a fixed width. Test any embed at 767px before you commit to it, and be prepared to constrain it with Custom CSS.
What a calculator has to say alongside its answer
A calculator produces a number, and a number is a claim. In most regimes it is treated as an illustration rather than a quotation, and it needs to say so.
The elements that generally survive review:
Every assumption, visible. Term, repayment type, interest basis, whether fees and insurance are included, and that the rate is illustrative.
A plain statement that the result is not a quotation, an offer, or a decision in principle, and that actual terms depend on assessment and lender criteria.
The date or rate basis used, so the figure can be understood later.
No implied approval. "You could borrow £420,000" is a very different sentence from "Based on the figures entered, a lender using these assumptions might consider a loan of around £420,000."
Nothing that captures identity data as a condition of seeing the result. Gating a calculator behind a form is a poor experience and it turns a generic tool into a personal illustration.
If your calculator vendor's default disclaimer does not cover these, replace it with your own text in an adjacent block rather than editing theirs.
The enquiry path, and the document problem
Mortgage enquiries convert on speed, so keep the form short: name, email, phone, purpose (purchase, remortgage, buy-to-let, product transfer), rough timescale, and one open field. Six fields. Everything else belongs in the fact-find, which happens after a human is involved.
Then a booked call. Acuity Scheduling — Squarespace's scheduling product, officially Acuity again and billed separately from your website plan — embeds through a scheduling block and handles the appointment. Its calendar limits run 1, 6 and 36 by tier, and it has no built-in waitlist, which for a broker taking one-to-one calls rarely matters.
Now the part that matters most: do not collect documents through your website.
Squarespace form blocks include a file upload field, capped at 10 MB per file and available only in form blocks — so technically you could receive payslips, bank statements and ID. Do not. Form submissions are stored in your Squarespace account and notified to you by email, and email is not an appropriate channel for identity documents, bank statements or income evidence. The same applies to free-text fields: no dates of birth, no national insurance or social security numbers, no account numbers, no full addresses of existing security.
The correct pattern is a two-stage one. The website collects enough to decide whether a call happens. After the call, documents move through whatever secure client portal, encrypted document exchange or lender platform your firm already uses. If you do not have one, that is the thing to buy before you buy a calculator.
The page set, and which templates already have it
A mortgage broker's site is a small, high-trust services site: Home, About with real photographs and credentials, Services split by scenario (first-time buyer, remortgage, buy-to-let, self-employed, adverse credit), a Process page, a Fees page, Calculators, FAQs, Contact with a booking route, plus the legal set — privacy, terms, complaints procedure where required, and any regulatory statements. Ten to twelve pages, all of which need review.
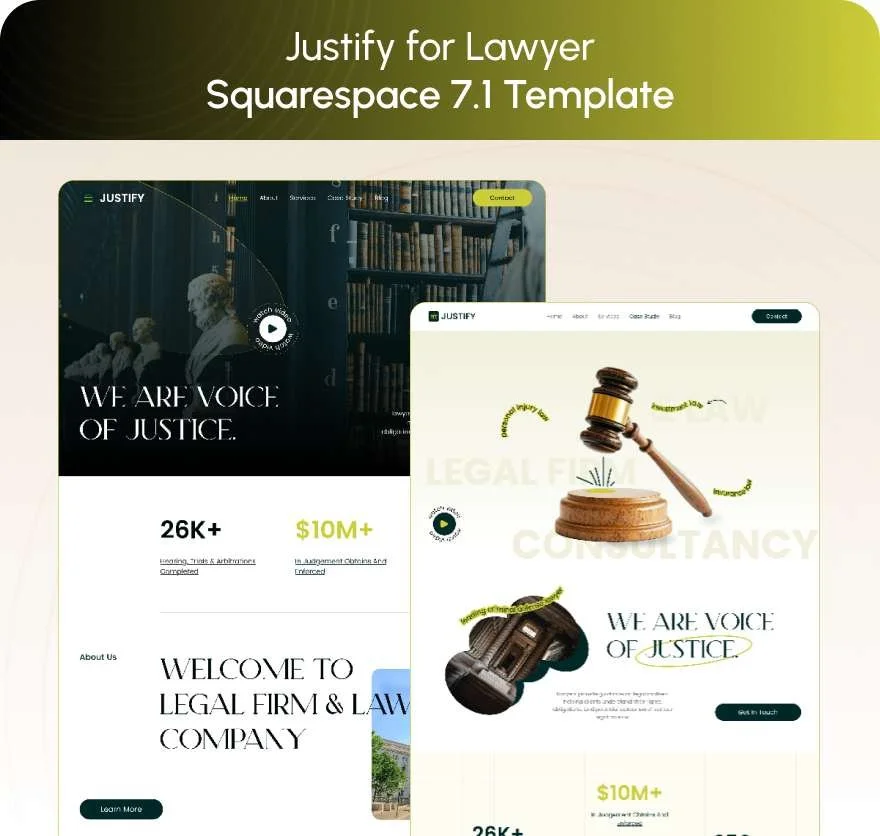
Justify (demo) is the smallest template in the Squareko shop at 9 pages and is structured for a professional-services firm: Home, About, Services, a practice-area page, a Case Study page, a Schedule a Call page, Blog and Contact, with a Style Guide and 404. The Schedule a Call page and the case-study structure are exactly the two a broker would otherwise build from scratch, and a small page count means a small review surface.
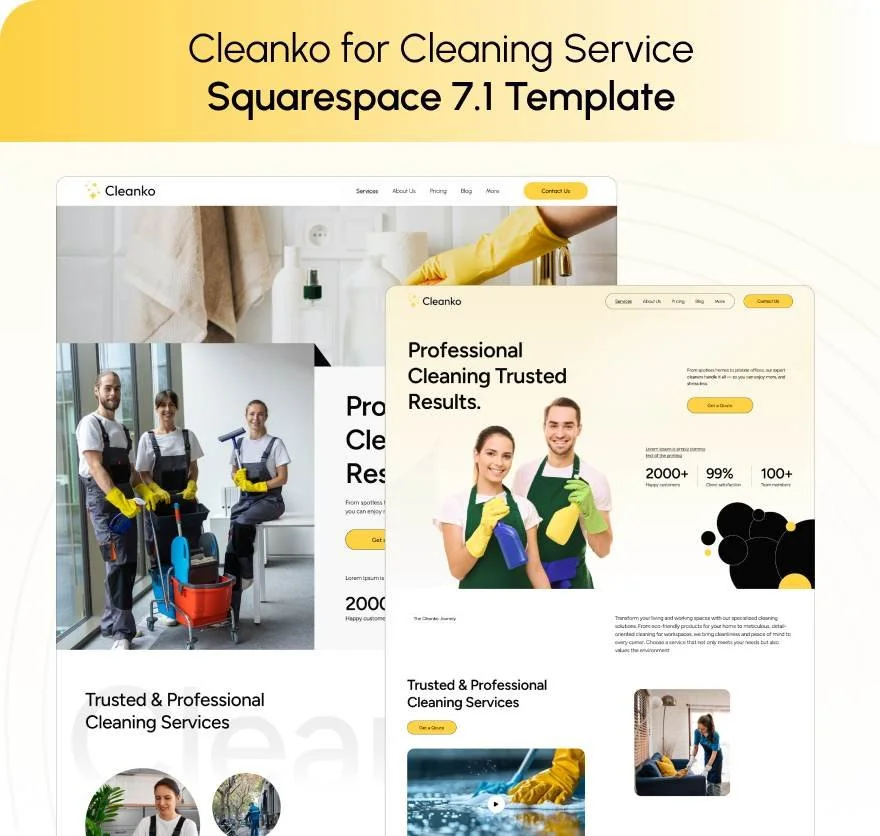
Cleanko (demo) runs to 12 pages with a Pricing page, a Service Details page and an FAQs page alongside Services, Portfolio, Blog and Contact. If you publish your fees — and you should — the Pricing page is already there.
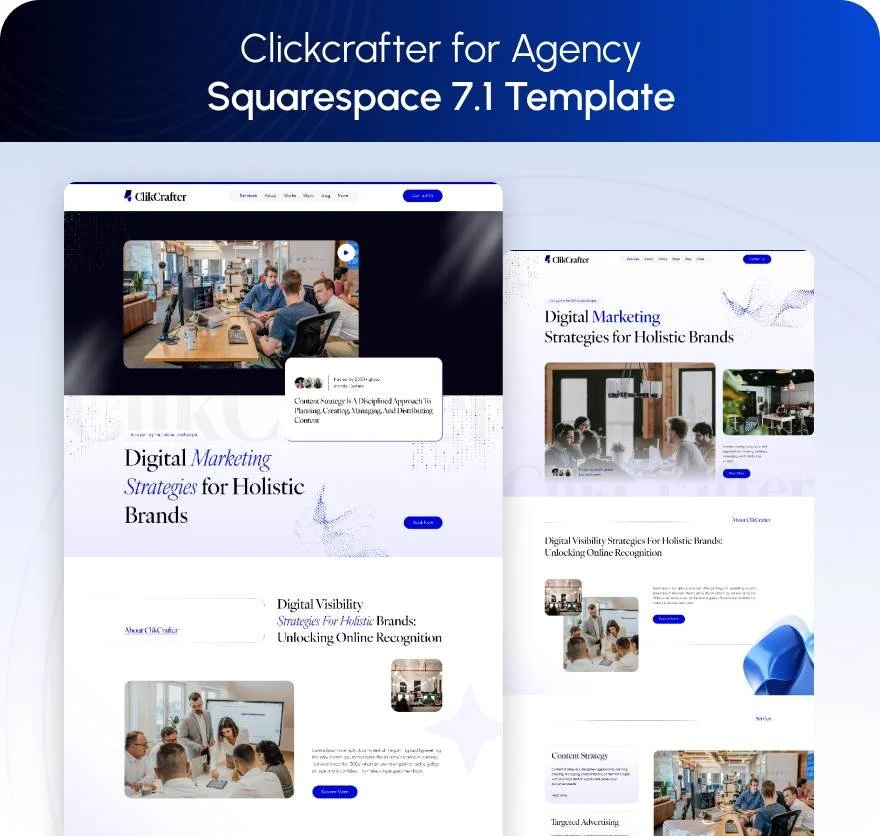
Click Crafter (demo) is a 12-page template with Blog, Portfolio and Gallery for a broker running a serious content programme aimed at first-time buyers.
Squareko's Advisory template is built on 11 pages including a Pricing page and two legal pages — the two page types financial sites most often bolt on badly. Its published demo link does not resolve, so judge it on that page list rather than a preview.
All Squareko templates are $249 with the Squarespace subscription paid separately, ship a Style Guide page and 150+ pre-designed sections, and arrive as a Squarespace contributor invitation rather than a file download. Demo images are not licensed for live use and must all be replaced.
Before you choose a template
Confirm your regulator and your licence category. Get the rates answer in writing. Decide whose calculator you are using and check your Squarespace plan supports it. Decide how documents will actually move. Then pick a template — and pick one whose page count you can afford to have reviewed.
If you would rather start from a page set that already includes pricing, FAQ and booking pages, our premium Squarespace templates are installed onto your site for you, so the build time goes into the copy that needs compliance review rather than the layout. Plenty of brokers do this themselves — the sequencing above is the part worth getting right either way.
FAQ
-
A calculator is JavaScript, so it goes in a Code Block as a vendor script or an iframe, or as your own custom-built HTML, CSS and JavaScript. JavaScript and iframes inside Code Blocks require the Core plan or above. The alternative on any plan is linking out to a lender's or regulator's calculator.
-
It is not broken. Squarespace disables script-bearing code blocks while you are logged in and editing, showing the message that embedded scripts are disabled. Use Preview in Safe Mode or view the page logged out. Always verify any embed logged out before debugging it.
-
It depends on your regulator, and in several regimes stating a rate or payment figure triggers mandatory additional disclosures on the same page. Under US Regulation Z, for example, stating a payment amount or repayment period requires disclosing repayment terms and the annual percentage rate. Confirm your own position in writing before publishing any figure.
-
Most regimes require some form of firm or originator identification on public communications, and several specify particular numbers and wording. Build it as a footer block using your registered legal entity name rather than your trading brand, and check it at Squarespace's 767px mobile breakpoint where legal blocks commonly become unreadable.
-
Technically yes — form blocks include a file upload field capped at 10 MB per file — but you should not. Form submissions are stored in your Squarespace account and notified by email, which is not an appropriate channel for payslips, bank statements or identity documents. Use a secure client portal after the call.
-
Home, About with credentials, Services split by scenario, Process, Fees, Calculators, FAQs and Contact with a booking route, plus privacy, terms and a complaints procedure where required. Around ten to twelve pages, each of which needs compliance review — a smaller page count means a smaller review surface.
Author Bio
I'm Walid Hasan, a Certified Squarespace Expert and Squarespace Circle Platinum Partner with over 12 years of hands-on experience designing and optimizing high-performing websites. Over the years, I've had the privilege of building more than 2,000 Squarespace websites for clients around the world, always focusing on clean design, strong user experience, and conversion-driven results.